Why the Polymarket TWAP 99 Sniper Bot Still Works After the TWAP Upgrade
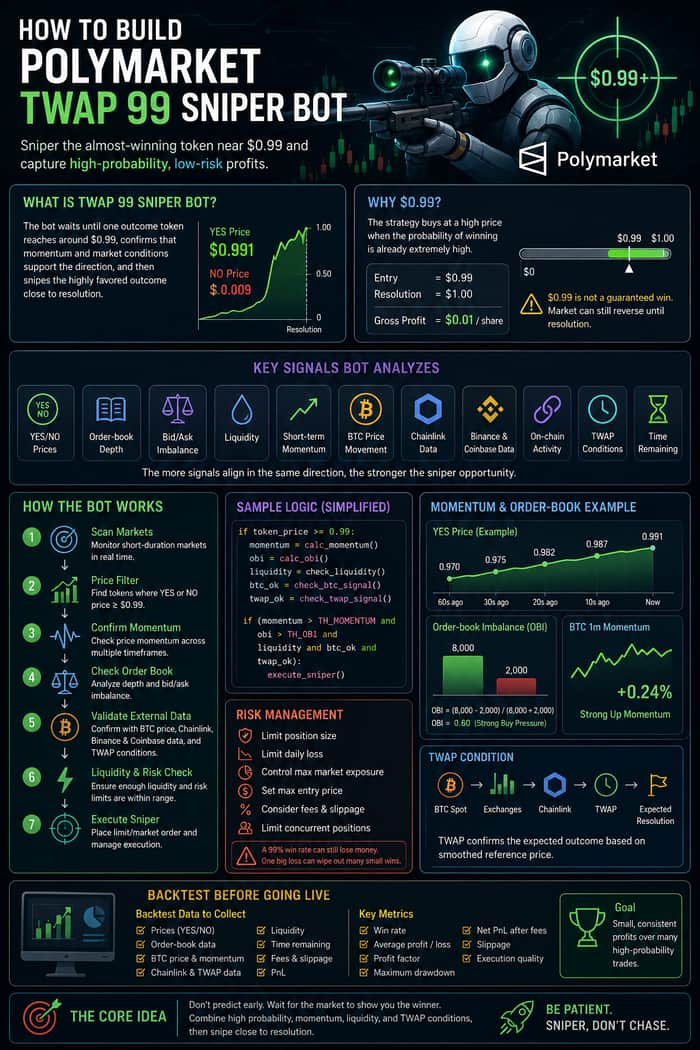
Polymarket’s TWAP upgrade changed the behavior of short-duration prediction markets. Prices became smoother, short-term noise was reduced, and some trading bots that depended on fast price movements became less effective.
But this creates an interesting question:
If the market became harder to predict with momentum alone, why does a 99¢ sniper strategy still make sense?
The answer is not simply “because the token is at $0.99.”
The interesting part is the combination of probability, time, market structure, and execution.
The Strategy Is About Late-Stage Probability
A typical market might look like:
YES = $0.991
NO  = $0.009
At this point, the market is already strongly favoring YES.
Instead of trying to predict the outcome five minutes earlier, the sniper waits until the market has already revealed its direction.
That creates a different trading model:
Traditional Bot
Prediction → Entry → Hope

99¢ Sniper
Observation → Confirmation → Entry
The bot is effectively paying a high price to reduce directional uncertainty.
The trade-off is obvious:
Higher probability, smaller potential profit.
Why the TWAP Upgrade Changes the Strategy
The TWAP upgrade makes the reference-price behavior smoother.
That matters because a sniper bot should care about the remaining path to resolution, not just the current token price.
For example, these two situations are very different:
A:
YES → 0.970 → 0.980 → 0.990 → 0.992

B:
YES → 0.995 → 0.992 → 0.988 → 0.984
Both reached the $0.99 area.
Only one has healthy momentum.
So the real question becomes:
Is $0.99 supported by the underlying market structure?
The Signal Stack
My approach is to treat the $0.99 level as a filter, not the entire strategy.
The bot analyzes:
- YES/NO prices
- Short-term momentum
- Order-book imbalance
- Liquidity
- BTC price movement
- Binance and Coinbase data
- Chainlink data
- TWAP conditions
- Time remaining
The architecture is roughly:
Token Price > $0.99
        ↓
Momentum
        ↓
Order Book
        ↓
Liquidity
        ↓
BTC / Chainlink
        ↓
TWAP Conditions
        ↓
Risk Check
        ↓
Execute
This is important because no individual signal is reliable enough on its own.
Why Order-Book Data Matters
Suppose YES is trading at $0.991.
That looks attractive for a sniper, but the order book might tell a different story.
A simple imbalance metric is:
obi = (bid_volume - ask_volume) / (
    bid_volume + ask_volume
)
If the order book continues showing strong support for YES, the $0.99 price becomes more meaningful.
If liquidity suddenly disappears or selling pressure increases, the bot can simply skip the trade.
That leads to one of the most important design principles:
A good sniper should be comfortable doing nothing.
Execution Is the Real Challenge
At $0.99, the theoretical profit is only around $0.01 per share if the token resolves at $1.00.
So execution can easily consume the edge.
For example:
Entry: $0.990
Resolution: $1.000
Gross edge: $0.010
But:
Entry: $0.997
Resolution: $1.000
Gross edge: $0.003
After fees and slippage, the second trade may no longer be attractive.
This is why I would consider the execution engine just as important as the signal engine.
The Interesting Engineering Problem
Building the strategy is relatively easy.
Building a reliable production bot is much harder.
The system needs to handle:
Market Data
     ↓
Signal Detection
     ↓
Risk Management
     ↓
Order Execution
     ↓
Fill Monitoring
     ↓
Reconciliation
     ↓
PnL Tracking
It also needs to deal with latency, partial fills, liquidity changes, rejected orders, and network failures.
In other words:
The strategy is only one component of the product.
The rest is distributed-system engineering.
What I Would Backtest
I would not optimize only for win rate.
A 99% win rate can still produce negative returns if one losing trade is large enough.
Instead, I would track:
- Average entry price
- Average profit
- Average loss
- Win rate
- Profit factor
- Maximum drawdown
- Slippage
- Fees
- Execution failures
- Net PnL
The goal is to answer a much more useful question:
Does the strategy still have positive expected value after real execution costs?
My Takeaway
The interesting thing about the TWAP 99 strategy isn't really the $0.99 price.
It is the idea of waiting until uncertainty has already decreased before committing capital.
The bot doesn't need to predict every market.
It needs to identify a small number of situations where:
Probability + momentum + liquidity + order-book structure + TWAP conditions + execution quality
all point in the same direction.
And that is why I see the TWAP 99 Sniper Bot less as a simple trading strategy and more as an engineering problem around probability and execution.
Don't try to predict the market too early. Let the market reveal the direction, then decide whether the remaining edge is worth paying for.
🤝 Collaboration & Contact
If you’re interested in building trading bots, buy trading bots, collaborating, exploring strategy improvements, or discussing about this system, feel free to reach out.
I’m especially open to connecting with:
Quant traders
Engineers building trading infrastructure
Researchers in prediction markets
Investors interested in market inefficiencies
📌 GitHub Repository
This repo has some Polymarket several bots in this system.
You can explore the full implementation, strategy logic, and ongoing updates about 5 min crypto market here:
https://github.com/Benjam1nCup/Polymarket-trading-bot-python-V2
💬 Get in Touch
If you have ideas, questions, or would like to collaborate or want these trading bots, don’t hesitate to reach out directly.
Feedback on your repo (based on your description & strategy)
Contact Info
Telegram
https://t.me/BenjaminCup
tags: #polymarket,#trading,#bot,#architecture,#tutorial,#TWAP
